ഓസ്ട്രേലിയൻ സൂപ്പർആനുവേഷൻ സമ്പൂർണ്ണ മാർഗ്ഗരേഖ 2026–27 Australian Superannuation Guide for Malayalees (12% SG & DASP)
ഇന്ത്യയിലെ പ്രൊവിഡന്റ് ഫണ്ട് (EPF/PF) സമ്പ്രദായവുമായി ഏറെ സാമ്യമുള്ളതും എന്നാൽ ഓസ്ട്രേലിയൻ നിക്ഷേപ വിപണിയുമായി നേരിട്ട് ബന്ധപ്പെട്ടു കിടക്കുന്നതുമായ സൂപ്പർആനുവേഷൻ പെൻഷൻ സംവിധാനത്തെക്കുറിച്ചുള്ള പ്രായോഗിക ഗൈഡ് - 12% നിർബന്ധിത തൊഴിലുടമ വിഹിതം, അക്കൗണ്ട് തെരഞ്ഞെടുപ്പ്, myGov വഴി നഷ്ടപ്പെട്ട സൂപ്പർ കണ്ടെത്തൽ, താല്കാലിക വിസക്കാർക്കുള്ള DASP പിൻവലിക്കൽ നിയമങ്ങൾ എന്നിവയെല്ലാം ഇതിൽ ഉൾപ്പെടുന്നു.
By Binu Vadakkedath
Last updated: September 2026 · Australian Financial Year 2026–27 · Sourced from ATO, APRA & Moneysmart
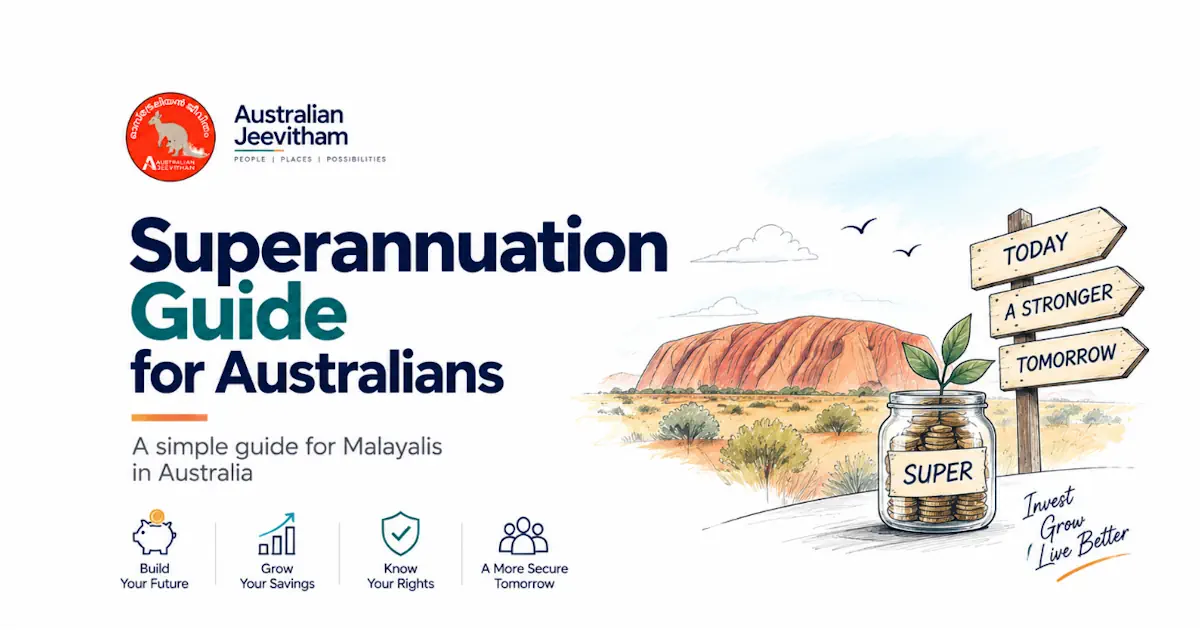
2026–27 സാമ്പത്തിക വർഷത്തിൽ Superannuation Guarantee (SG) നിരക്ക് 12% ആണ്. 1 July 2026 മുതൽ Payday Super നിയമപ്രകാരം SG കണക്കാക്കാൻ പുതിയ “qualifying earnings” (QE) അടിസ്ഥാനമാണ് ഉപയോഗിക്കുന്നത്. Employers contribute this compulsory amount into your complying super fund.
- 12% SG Rate
- EPF vs Super
- Stapled Funds
- myGov Consolidation
- Concessional Caps
- DASP (Temporary Visas)
- Industry vs Retail Funds
- Default Insurance
This guide is for informational purposes only and does not constitute financial, legal, or migration advice. Superannuation legislation, indexation caps, and tax thresholds are determined by the Australian Government and Australian Taxation Office (ATO). Always verify current figures at ato.gov.au or consult an authorised financial adviser for personalised retirement planning. സാമ്പത്തിക തീരുമാനങ്ങൾ എടുക്കുന്നതിന് മുൻപ് ഔദ്യോഗിക വിവരങ്ങൾ എപ്പോഴും പരിശോധിക്കുക.
1. എന്താണ് സൂപ്പർആനുവേഷൻ? അടിസ്ഥാന കാര്യങ്ങൾ (Superannuation Foundations)
ഓസ്ട്രേലിയയിൽ ജോലി ചെയ്യുന്ന ജീവനക്കാർക്ക് അവരുടെ വിരമിക്കൽ കാലത്തേക്ക് സമ്പാദ്യം ഉറപ്പാക്കുന്നതിനായി തൊഴിലുടമകൾ നിർബന്ധമായും നൽകേണ്ട പെൻഷൻ സമ്പാദ്യ പദ്ധതിയാണ് സൂപ്പർആനുവേഷൻ (Super). ഈ തുക സാധാരണ ശമ്പളത്തോടൊപ്പം നേരിട്ട് കൈയിൽ നൽകുന്നതല്ല; പകരം നിങ്ങളുടെ തെരഞ്ഞെടുക്കപ്പെട്ട അല്ലെങ്കിൽ സ്റ്റേപ്പിൾഡ് (Stapled) സൂപ്പർ ഫണ്ടിലേക്കാണ് കമ്പനികൾ നിക്ഷേപിക്കുന്നത്.
- Superannuation Guarantee (SG) Rate: The compulsory SG rate is 12%. From 1 July 2026, Payday Super uses qualifying earnings (QE) to calculate SG. QE includes OTE and certain other payments specified by the new rules.
- Qualifying Earnings (QE): 1 July 2026 മുതൽ SG calculation-ന് OTE മാത്രം എന്ന പഴയ framing ഉപയോഗിക്കരുത്. പുതിയ QE definition OTE-യും salary-sacrificed OTE-യും നിയമത്തിൽ ഉൾപ്പെടുത്തിയിട്ടുള്ള മറ്റ് ചില earnings/payments-ഉം ഉൾക്കൊള്ളുന്നു. ഓരോ payment type-നും current ATO guidance പരിശോധിക്കുക.
- No $450 Monthly Threshold: The former rule requiring a worker to earn at least $450/month before qualifying for super was abolished on 1 July 2022. Eligible casual, part-time, and full-time workers qualify regardless of monthly income.
- Under 18 Rule: 18 വയസ്സിന് താഴെയുള്ള ജീവനക്കാർ ആഴ്ചയിൽ 30 മണിക്കൂറിൽ കൂടുതൽ ജോലി ചെയ്യുന്നുണ്ടെങ്കിൽ മാത്രമേ അവർക്ക് തൊഴിലുടമ സൂപ്പർ നൽകേണ്ടതുള്ളൂ. വിരമിക്കൽ പ്രായത്തിന് മുകളിലുള്ള മുതിർന്ന ജീവനക്കാർക്കും സൂപ്പർ ആനുകൂല്യം ലഭിക്കും.
Payday Super - effective 1 July 2026: Payday Super is now in effect. Employers must calculate SG when qualifying earnings are paid and make the contribution on payday. In the usual case, the contribution must be received by the employee's super fund within 7 business days, although longer statutory timeframes apply in specified circumstances such as some new-employee and fund-change situations. The former quarterly SG framework applies to periods before the reform and should not be presented as the current 2026–27 rule.
2. താല്കാലിക വിസക്കാർ, വിദ്യാർത്ഥികൾ & വർക്കിംഗ് ഹോളിഡേ (Temporary Residents)
Temporary visa holder ആണെന്ന കാരണത്താൽ മാത്രം employer SG entitlement ഇല്ലാതാകില്ല. നിങ്ങൾ SG rules പ്രകാരം eligible worker ആണെങ്കിൽ employer compulsory super നൽകണം; eligibility നിങ്ങളുടെ employment circumstances-നെയും applicable super law-നെയും ആശ്രയിച്ചിരിക്കും.
- Student Visa Holders (Subclass 500): International students who are eligible workers under the SG rules can receive compulsory 12% SG contributions. The 48-hour fortnightly work limitation during study terms is an immigration visa condition, not a superannuation barrier.
- Working Holiday Makers (Subclass 417 & 462): വർക്കിംഗ് ഹോളിഡേ വിസക്കാർക്കും തൊഴിലുടമകൾ കൃത്യമായി സൂപ്പർ നൽകണം. ഇവരുടെ ശമ്പള വരുമാനത്തിന് പ്രത്യേക നികുതി നിരക്കുകൾ ബാധകമാണെങ്കിലും, സൂപ്പർ നിക്ഷേപ തത്വങ്ങൾ മാറ്റമില്ലാതെ തുടരുന്നു.
- Contractors Paid for Labour: നിങ്ങൾ ഒരു ABN ഉപയോഗിച്ച് പ്രധാനമായും സ്വന്തം കായിക/മാനസിക അധ്വാനം (Labour) മാത്രം വിൽക്കുന്ന കോൺട്രാക്ടറായി ജോലി ചെയ്യുകയാണെങ്കിൽ പോലും ചില സാഹചര്യങ്ങളിൽ തൊഴിലുടമ സൂപ്പർ നൽകാൻ ബാധ്യസ്ഥനാണ്.
3. ഇന്ത്യൻ PF/EPF vs ഓസ്ട്രേലിയൻ സൂപ്പർ (Core Differences)
ഇന്ത്യയിലെ എംപ്ലോയീസ് പ്രൊവിഡന്റ് ഫണ്ടും (EPF) ഓസ്ട്രേലിയൻ സൂപ്പർആനുവേഷനും തമ്മിലുള്ള പ്രധാന വ്യത്യാസങ്ങൾ താഴെ കാണുന്ന പട്ടികയിലൂടെ എളുപ്പത്തിൽ മനസ്സിലാക്കാം:
| ഫീച്ചർ (Feature) | ഇന്ത്യൻ EPF / PF | ഓസ്ട്രേലിയൻ സൂപ്പർ (Super) |
|---|---|---|
| നിർബന്ധിത വിഹിതം (Mandatory Contribution) | EPF-covered employment-ൽ employee contribution സാധാരണയായി wages-ന്റെ 12% ആണ്; employer-ന്റെ statutory contribution-വും സാധാരണ 12% ആണെങ്കിലും അതിന്റെ allocation EPF/EPS rules അനുസരിച്ച് മാറാം. | തൊഴിലുടമ മാത്രം നിർബന്ധിത 12% SG (Qualifying Earnings അടിസ്ഥാനത്തിൽ) അടയ്ക്കുന്നു; ജീവനക്കാരൻ സ്വന്തം ശമ്പളത്തിൽ നിന്ന് നിർബന്ധമായി അടയ്ക്കേണ്ടതില്ല. |
| അക്കൗണ്ട് തരം (Account Type) | EPF balance-ന് EPFO/Government process പ്രകാരം വർഷംതോറും പ്രഖ്യാപിക്കുന്ന interest rate ബാധകമാണ്; market-linked അല്ല. | Most members have accumulation accounts, where contributions and investment returns determine the balance. Some members hold defined benefit accounts, where benefits are calculated under a fund formula. |
| ഫണ്ട് തെരഞ്ഞെടുപ്പ് (Fund Choice) | EPFO അല്ലെങ്കിൽ കമ്പനി ട്രസ്റ്റ് (ജീവനക്കാരന് ഫണ്ട് മാറ്റാൻ കഴിയില്ല). | മിക്ക eligible ജീവനക്കാർക്കും Choice of Fund അവകാശമുണ്ട്; Industry, Retail, SMSF തുടങ്ങിയ options തിരഞ്ഞെടുക്കാം. |
| ഡീഫോൾട്ട് സമ്പ്രദായം (Default / Stapling) | UAN (Universal Account Number) വഴി കമ്പനി മാറുമ്പോൾ ലിങ്ക് ചെയ്യപ്പെടുന്നു. | ജീവനക്കാരൻ fund choice നൽകാത്തപ്പോൾ employer ATO-യിൽ stapled super fund ഉണ്ടോ എന്ന് പരിശോധിക്കണം. |
| നികുതി ഘടന (Taxation) | EPF contributions & withdrawals-ന്റെ tax treatment നിബന്ധനകൾക്ക് വിധേയമാണ്. | Concessional contributions are generally taxed at 15%; investment earnings in an accumulation account are taxed at up to 15%. Additional tax and other exceptions can apply. |
| പിൻവലിക്കൽ (Withdrawal) | വിരമിക്കൽ പ്രായം എത്തുന്നതുവരെ അല്ലെങ്കിൽ ജോലി വിട്ട് നിശ്ചിത കാലയളവിനു ശേഷം വ്യവസ്ഥകൾക്ക് വിധേയമായി പിൻവലിക്കാം. | വിരമിക്കൽ പ്രായം (Preservation Age) എത്തുന്നതുവരെ തുക ലോക്ക്ഡ് ആയിരിക്കും. |
| പ്രവാസി മടക്കം (Departure Access) | EPFO rules അനുസരിച്ച് വ്യവസ്ഥകൾക്ക് വിധേയമായി അപേക്ഷിക്കാം. | Eligible former temporary residents may claim a DASP. Withholding depends on the payment component and Working Holiday Maker status, with current rates of 0%, 35%, 45% or 65%. |
4. ഫണ്ട് തരങ്ങളും ഇൻഷുറൻസും (Industry vs Retail Funds)
Understanding where your retirement money is invested and regulated.
Industry Super Funds
Many industry funds operate on a profit-for-members model. Compare fees, investment options, long-term performance, insurance and services rather than choosing solely by the “industry” label.
Retail Super Funds
Retail funds are generally offered by financial-services businesses and may provide broad investment and advice options. Compare the product itself - including fees, performance, insurance and services.
Self-Managed Super (SMSF)
Private funds for up to 6 members who act as trustees, regulated directly by the ATO with full responsibility for legal compliance and reporting.
ഡീഫോൾട്ട് ഇൻഷുറൻസ് പരിരക്ഷ (Insurance Inside Super)
പല super funds-ലും eligible members-ക്ക് Death Cover, TPD, ചിലപ്പോൾ Income Protection എന്നിവ ലഭിക്കാം; automatic/default cover age, balance, activity status, fund rules എന്നിവയെ ആശ്രയിച്ചിരിക്കും. ഇതിന്റെ പ്രീമിയം തുക നിങ്ങളുടെ സൂപ്പർ ബാലൻസിൽ നിന്നാണ് കിഴിക്കുന്നത്. ഒന്നിലധികം അക്കൗണ്ടുകൾ ഉണ്ടെങ്കിൽ ഡ്യൂപ്ലിക്കേറ്റ് പ്രീമിയം കാരണം നിങ്ങളുടെ ബാലൻസ് ചോർന്നുപോകാൻ സാധ്യതയുണ്ട്.
Default insurance generally does not start automatically for a new member who is under 25 or whose balance is below $6,000, unless an exception applies or the member opts in. Check the fund's product disclosure statement and your account before relying on any cover.
5. സൂപ്പർ നികുതികളും പരിധികളും (Tax Rules & Contribution Caps)
Australian superannuation enjoys concessional tax treatment compared to standard marginal income tax brackets. Contributions fall into two primary categories:
- Concessional Contributions (Pre-Tax): Includes employer SG payments, salary sacrifice, and personal deductible contributions. Generally taxed at a flat 15% inside the fund. The general concessional contributions cap is $30,000 for 2026–27.
- Carry-Forward Rule: അർഹതയുള്ളവർക്ക് മുൻ 5 വർഷങ്ങളിലെ unused concessional cap amounts carry forward ചെയ്യാൻ സാധിക്കാം. സാധാരണയായി previous 30 June-ലെ Total Super Balance $500,000-ൽ താഴെയായിരിക്കണം.
- Non-Concessional Contributions (After-Tax): Personal contributions made from after-tax income. The general annual non-concessional cap is $120,000 for 2026–27, subject to eligibility and bring-forward rules.
- Investment Earnings Tax: Earnings in accumulation accounts are taxed at a maximum of 15% (with long-term capital gains discounted to 10%).
- Division 293: An additional 15% tax can apply to certain concessional contributions when the relevant Division 293 income and super contributions exceed the $250,000 threshold.
6. നഷ്ടപ്പെട്ട സൂപ്പർ കണ്ടെത്താനും ഒരുമിപ്പിക്കാനും (Consolidation via myGov)
ഓസ്ട്രേലിയയിൽ ജോലി മാറുമ്പോൾ ഒന്നിലധികം സൂപ്പർ അക്കൗണ്ടുകൾ തുറക്കപ്പെടാൻ സാധ്യതയുണ്ട്. ഓരോ അക്കൗണ്ടിലും പ്രത്യേകം അഡ്മിനിസ്ട്രേഷൻ ഫീസും ഇൻഷുറൻസ് ചാർജും നൽകേണ്ടി വരുന്നത് ഭാവി സമ്പാദ്യത്തെ കാര്യമായി ബാധിക്കും. myGov വഴി ഇത് ലളിതമായി പരിഹരിക്കാം:
- Sign In to myGov: Log into your official myGov account and ensure the Australian Taxation Office (ATO) service is linked.
- Navigate to Super: ATO പോർട്ടൽ തുറന്ന് 'Super' മെനുവിലേക്ക് പോവുക. അവിടെ നിങ്ങളുടെ നിലവിലെ എല്ലാ അക്കൗണ്ടുകളും, മുൻകാല തൊഴിലുടമകൾ നിക്ഷേപിച്ച തുകകളും, ATO കൈവശം വെച്ചിരിക്കുന്ന Lost Super വിവരങ്ങളും കാണാം.
- Review & Verify: Confirm your personal details (legal name, date of birth, previous employer records).
- Check Benefits Before Transferring: Before closing or transferring an account, check whether you could lose life, TPD or income-protection insurance, defined-benefit rights, or employer contribution arrangements. Confirm any replacement insurance is active before cancelling existing cover.
- Consolidate: Select the transfer tool in myGov to combine multiple balances into your chosen primary super fund.
- Notify Employer: ഒരുമിപ്പിച്ച ശേഷം പുതിയ ഫണ്ട് വിവരങ്ങൾ നിലവിലെ തൊഴിലുടമയ്ക്ക് നൽകി തുടർന്നുള്ള 12% SG വിഹിതം കൃത്യമായി എത്തുന്നുണ്ടെന്ന് ഉറപ്പാക്കുക.
7. പണം പിൻവലിക്കലും DASP നിയമങ്ങളും (Access & Departing Australia Super)
Super is preserved until a statutory condition of release is satisfied. Preservation age depends on date of birth and is 60 for anyone born after 30 June 1964. Reaching preservation age does not by itself release the money: a condition such as retirement must also be met. Super can generally be accessed from age 65 regardless of retirement status. It cannot be withdrawn simply for living expenses or job changes.
Departing Australia Superannuation Payment (DASP)
ഓസ്ട്രേലിയയിൽ താല്കാലിക വിസയിൽ (Student / 482 / 485 / Working Holiday) ജോലി ചെയ്ത ശേഷം eligible former temporary residents-ക്ക് Australia വിട്ട ശേഷം അവരുടെ temporary visa ceased ആയാൽ DASP വഴി super claim ചെയ്യാൻ സാധിക്കാം. എന്നാൽ ഇതിന് കർശനമായ നിബന്ധനകളുണ്ട്:
- You must have accumulated super while working in Australia on an eligible temporary resident visa.
- Your temporary visa must have ceased, for example because it expired or was cancelled.
- You must have left Australia and must not hold another active Australian visa. You do not have to return specifically to your country of citizenship.
- You must not be an Australian or New Zealand citizen or an Australian permanent resident. Use the ATO DASP eligibility check for your circumstances.
| വിസ തരം (Visa Category) | DASP നികുതി നിരക്ക് (Tax Deducted) |
|---|---|
| Non-WHM DASP - taxable component (taxed element) | 35% DASP withholding tax. |
| Non-WHM DASP - taxable component (untaxed element) | 45% നികുതി ബാധകം. |
| DASP subject to Working Holiday Maker rate | 65% on the taxable component (taxed and untaxed elements). |
| Tax-free component | 0% DASP withholding tax. |
8. പുതിയ പ്രവാസികൾ ഒഴിവാക്കേണ്ട പ്രധാന തെറ്റുകൾ (Common Pitfalls to Avoid)
1. താല്കാലിക അവധിക്ക് പോകുമ്പോൾ DASP അപേക്ഷിക്കുക: വിസ പ്രാബല്യത്തിൽ ഉള്ളപ്പോൾ നാട്ടിലേക്ക് വെക്കേഷന് പോകുമ്പോൾ DASP ക്ലെയിം ചെയ്യാൻ സാധിക്കില്ല. വിസ റദ്ദാക്കപ്പെടുകയോ കാലാവധി കഴിയുകയോ വേണം.
2. ഇൻഷുറൻസ് പരിശോധിക്കാതെ അക്കൗണ്ടുകൾ ഒരുമിപ്പിക്കുക: പഴയ അക്കൗണ്ടുകൾ യാന്ത്രികമായി ക്ലോസ് ചെയ്യുമ്പോൾ വിലപ്പെട്ട ഡിസബിലിറ്റി/ലൈഫ് ഇൻഷുറൻസ് പരിരക്ഷകൾ നഷ്ടപ്പെട്ടേക്കാം. കൺസോളിഡേഷന് മുൻപ് പരിശോധിക്കുക.
3. കാഷ്-ഇൻ-ഹാൻഡ് ജോലികളിൽ സൂപ്പർ നഷ്ടപ്പെടുത്തൽ: Cash ആയി wage നൽകുന്നത് മാത്രം illegal അല്ല. പക്ഷേ employer minimum pay, payslip, tax/record-keeping, SG തുടങ്ങിയ നിയമബാധ്യതകൾ പാലിക്കണം. ATO/myGov-ൽ actual super contributions എത്തിയിട്ടുണ്ടോ എന്നും പരിശോധിക്കുക.
ഔദ്യോഗിക വെബ്സൈറ്റുകൾ (Official Resources)
സൂപ്പർ വിവരങ്ങൾ പരിശോധിക്കാൻ ഔദ്യോഗിക സർക്കാർ പോർട്ടലുകൾ മാത്രം ഉപയോഗിക്കുക:
Bookmark these verified government domains:
More on settlement, employment & life in Australia
First 30 Days in Australia
A day-by-day settlement checklist covering SIM, bank account, TFN, Medicare, myGov, WWCC, and the childcare subsidy trap to avoid.
- Settlement Guide
- TFN & Medicare
- New Arrivals
Resume & Cover Letter Guide
ATS-friendly formatting, tailored cover letters, selection criteria and STAR examples for Malayalis applying for Australian jobs.
- ATS-Friendly
- STAR Examples
- Job Applications
Malayalam Resources Hub
A comprehensive directory of guides covering jobs, visas, healthcare registration, licence conversion, superannuation, and settling into Australia.
- 11+ Guides
- Jobs & Visas
- Settlement